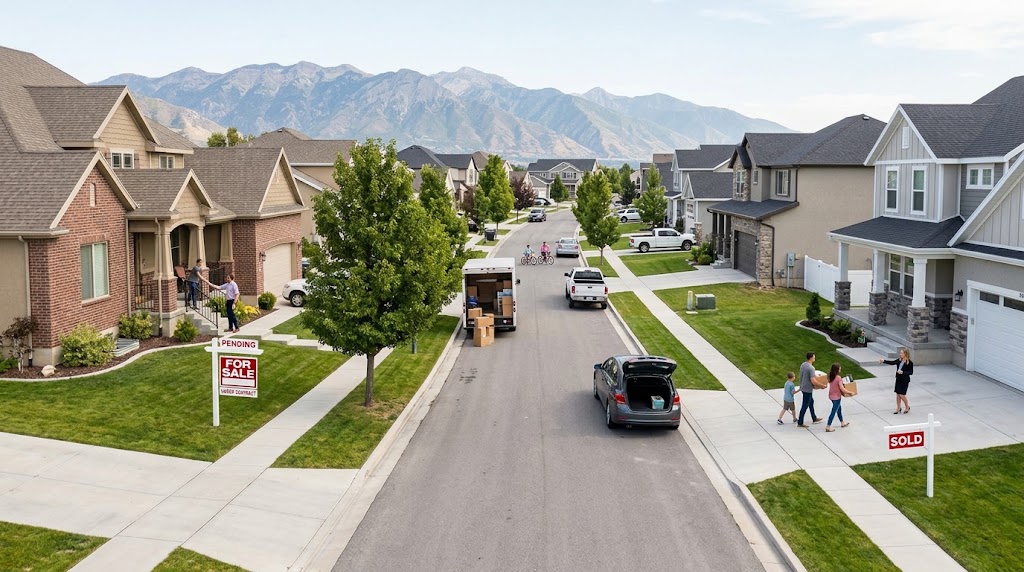
Need to sell your South Jordan home and buy the next one without the dates colliding? Start with one question: does your next purchase depend on the money or the loan approval from your current sale?
That answer usually decides the order. If the next home depends on your sale, selling first, or tying your offer to your sale, tends to make sense. If it doesn’t, buying first may be possible, but only after a lender confirms you can carry both homes for a while. Either way, the hardest part isn’t choosing an order. It’s lining up two contracts’ worth of dates, and knowing that signing, funding, recording, and moving in are four different moments. Here’s how I’d map it with you, so you know where the gaps are before you list.
Sell First, Buy First, or Overlap
Each path has a different kind of risk. None of them makes the move from one home to the next easy on its own.
Should You Sell Your South Jordan Home Before Offering on the Next One?
Selling first is the path that gives you the most certainty about money. Once your sale closes, you know what came out of it, and you’re shopping with that in hand instead of with an estimate.
The tradeoff is the in-between. If your sale closes before you’ve found and closed on the next home, you need somewhere to live and somewhere to put your things.
Selling first can fit you if
- Your next down payment or loan approval depends on your sale.
- You’d rather know your numbers before you shop seriously.
- You have a realistic short-term housing option, like family, a short rental, or a negotiated stay in your current home after closing.
Questions to answer before you list
- Where would you live if there’s a gap, and for how long could that work?
- Where would your belongings go? Would you need storage?
- Would you ask your buyer for time in the home after closing? If so, that needs to be written into the contract.
I’d never assume a stay-after-closing arrangement will just happen. If you want time after recording, the REPC has possession choices for that, and a rental arrangement requires a separate written agreement. I’ll explain both below.
What Changes If You Buy First Instead?
Buying first lets you move once, straight into the next home. It also means you could own two homes, and owe on both, until your current one sells.
That’s a lending question before it’s a real estate question. Before you shop seriously, sit down with a lender and ask whether you can qualify for and carry the new loan while you still own your current home.
Financing terms you may hear
Lenders may talk about ways to use the equity in your current home before it sells. Two terms you’re likely to hear:
- HELOC. The Consumer Financial Protection Bureau describes a home equity line of credit as borrowing against the equity in your home. The CFPB also warns that if you can’t repay, you could risk losing the home.
- Bridge loan. A temporary loan some lenders offer to bridge the gap between buying and selling. Whether one is available to you, and on what terms, is entirely up to the lender.
I won’t tell you whether either one is right for you, and I won’t quote rates or costs. That conversation belongs with your lender. My job is to make sure your timeline fits whatever your lender approves.
Buying first can fit you if
- A lender has confirmed in writing that you can carry both homes for a period.
- You’re comfortable with the risk that your current home takes longer to sell than you’d like.
- Avoiding a temporary move matters more to you than certainty about your sale proceeds.
What Move-Up Homeowners Commonly Get Wrong About Selling and Buying
These assumptions cause most of the stress I see in two-home moves. Each one has a better plan behind it.
| What People Assume | What the Contract or Regulator Says | What to Plan Instead |
|---|---|---|
| “I’ll close both on the same day and move straight in.” | The REPC separates settlement, closing (funding and recording), and possession. They don’t have to happen at the same moment. | Build buffers between each step, and write possession timing into both contracts. |
| “Once my sale is accepted, I can use the money.” | An accepted offer is the start of a contract. Funds move at closing, which includes funding and recording. | Don’t plan to spend sale proceeds until your sale has actually closed. |
| “Signing at settlement means I own the new home.” | Section 3.1 defines settlement. Section 3.2 defines closing, which includes loan funding and recording, separately. | Confirm with title and your lender when funding and recording will happen. |
| “My loan can close the moment I’m ready.” | The CFPB says typical mortgage borrowers must receive a Closing Disclosure at least three business days before closing, with some exceptions. | Put that review window on your calendar. |
| “A sale contingency always protects my deposit.” | Section 2.2 lets you indicate a sale condition, but the details live in a separate addendum. | Read the addendum, and ask an attorney about your rights. |
| “A bridge loan is easy to get.” | Availability and terms depend on the lender. The CFPB warns that borrowing against your home puts it at risk if you can’t repay. | Talk to a lender before you plan around any bridge product. |
When Does a Home-Sale Contingency Belong in the Plan?
Utah’s state-approved purchase contract lets you tie your next purchase to the sale of your current home. Section 2.2 of the REPC lets a buyer indicate whether the purchase, financing, or cash depends on selling a home they already own. If you check yes, it points to a separate addendum that spells out the details.
That’s a real option, and it can be the right one. It also has to be written carefully, because the addendum is what controls how it works.
When I’d consider it
- Your next purchase genuinely depends on your current sale.
- You’d rather not move twice, and you don’t want to carry two homes.
- Your current home is ready to list, or already listed.
What to understand going in
A seller weighing your offer will be comparing it with others. A sale condition adds a question for them: will your home sell in time? I can’t tell you how any particular South Jordan seller will feel about that, and it would be wrong to say sellers always reject these offers. Some sellers may be fine with it. Others may prefer a buyer without that condition.
What you can control is how ready your current home is. A home that’s listed, or already under contract, makes the condition easier to understand.
And please don’t treat a sale contingency as a guarantee for your earnest money. Whether your deposit is protected depends on how the addendum is written and whether you meet the deadlines. That’s a question for the actual documents, and for an attorney if you need legal advice.
Which Contract Dates Need to Line Up Across Both Homes?
When you sell and buy at once, you’re living inside two REPCs. Each one has the same four deadlines in Section 24. The trick is to see both sets side by side.
Under Section 21, timing is essential. A deadline usually lands at 5 p.m. Mountain Time on its date unless your contract says something different, and any extension has to be written. With two contracts running, that rule applies twice. These dates are the gates your move has to pass through.
How I’d read the two calendars
- Put both sets of four dates on one page, sale side on the left and purchase side on the right.
- Mark which purchase-side dates depend on something happening on the sale side first.
- Look for any purchase-side deadline that falls before the sale-side event it depends on. That’s a gap.
- Decide how to close each gap: move a date, add a condition, or change the order.
This sounds tedious. It takes about an hour, and it’s the hour that prevents most two-home headaches.
Who to keep in the loop
Two contracts mean more people with a piece of the timeline. I’d make sure each of them can see the dates that affect them:
- Your lender, for the purchase-side financing and appraisal dates and the Closing Disclosure review window.
- The title or closing teams on both deals, for settlement, funding, and recording timing.
- Your buyer’s agent and the next seller’s agent, so a change on one side is known on the other right away.
When everyone sees the same calendar, a slip on one side gets noticed in time to fix it, instead of on moving day.
Why Settlement, Recording, and Possession Are Not the Same Event
This is the part most homeowners haven’t heard before, and it’s the one that causes the “we have the moving truck but no keys” days.
Settlement
Section 3.1 of the REPC describes settlement as signing and delivering the documents and delivering the funds each party owes. It’s the signing moment.
Funding
The lender releases the loan money. Section 3.2 includes funding as part of closing.
Recording
The transfer is recorded. Section 3.2 says funding and recording must happen no later than four calendar days after settlement, under the form’s terms.
Possession
When you actually get the home. Section 3.3 lets the parties choose, such as upon recording, or a number of hours or days afterward.
Put those together and you can see the risk. If you sign on your sale and your purchase on the same day, you may not have the keys to the new home that same day. Possession depends on what’s written in the contract, and funding and recording can take up to the time the form allows.
The CFPB adds one more piece on the loan side. For a typical mortgage, borrowers must receive a Closing Disclosure at least three business days before closing, with some exceptions. That review window belongs on your calendar too.
What this means for moving day
- Don’t book a moving truck for the day you sign. Book it for when possession is written to happen.
- If you need a few days in your current home after your sale, put it in the sale contract’s possession terms.
- If you’d stay longer as a renter, Section 3.3 says a rental needs a separate written agreement.
- Ask title and your lender for their expected funding and recording timing on both deals.
Where this comes from: contract details come from Utah’s state-approved Real Estate Purchase Contract, listed by the Utah Division of Real Estate and marked effective December 2024: Section 2.2 (sale condition), Sections 3.1 through 3.3 (settlement, closing, possession), and Sections 21 and 24 (deadlines). Closing Disclosure timing and HELOC risk come from the Consumer Financial Protection Bureau. This is general education. Your signed contracts, your lender, title, and an attorney decide how it applies to you.
How I’d Make a Two-Home Timeline With a Backup Plan
Here’s how I’d plan it with you, step by step, before your South Jordan home goes on the market.
Start with the lender
Find out whether your next purchase depends on your sale, and whether you can carry both homes for any period. This one answer picks your path.
Choose the path
Sell first, buy first, or overlap, based on the lender’s answer and how much a temporary move would disrupt you.
Get your current home ready
Whatever path you choose, a home ready to list keeps your options open, especially if you’ll use a sale condition.
Build the paired calendar
Lay out both sets of four deadlines. Mark the dependencies and find the gaps before you sign either contract.
Write possession on purpose
Decide when you leave the current home and when you get the next one, and put both in writing. Add buffers.
Plan the fallback
Decide now where you’d go and where your things would go if one deal slips by a few days or more.
The backup plan, in plain terms
Every two-home plan should answer three “what ifs” before anything is signed:
- What if my buyer’s loan is delayed? Know which purchase-side dates depend on your sale, and whether you could ask for a written extension.
- What if my purchase is delayed? Know whether you can stay in your current home a little longer, and how that’s written into your sale.
- What if both slip? Know your short-term housing and storage options before you need them.
Where timing judgment matters most: in 36 years of helping Utah families make move-up purchases, the sequence that holds up best is the one with buffers built in from the start. Same-day everything looks efficient on paper. A few days of planned overlap, written into both contracts, is usually what keeps moving day calm.
What a buffered sequence can look like
Here’s one shape a sell-first plan with a small overlap can take. Your dates will be your own; this is about the order of events, not the timing.
- Talk with your lender and pick your path.
- Prepare and list your current home.
- Accept an offer on your current home, with possession terms that give you a little time after recording.
- Write your offer on the next home with a Settlement Deadline after your sale’s expected closing, plus room for funding and recording.
- Watch both sets of deadlines side by side, and get any change in writing right away.
- Close your sale, then your purchase, then move on the possession date you wrote into the contract.
The details change from family to family. The principle doesn’t: each step should have a little room before the next one depends on it.
What Should You Have Ready Before You List?
Most two-home stress starts with a question nobody asked early enough. Before your South Jordan home goes on the market, I’d want these settled:
A lender conversation
Whether the next purchase depends on your sale, and what you can qualify for either way. This picks your path.
Your move window
The range of dates that would work for your household, including school, work, and anything else that can’t move.
A fallback place to stay
Where you’d go if your sale closes first and the next home isn’t ready yet.
A storage plan
Where your belongings would go for a short gap, and how quickly you could arrange it.
Title and closing contacts
Who will handle each closing, so you can ask about funding and recording timing early.
Your must-haves for the next home
A clear list, so you’re ready to write an offer when the right home appears.
None of these require a decision about the next home yet. They just make sure you’re not answering urgent questions under pressure later.
For more on selling and buying in the city, my South Jordan housing guide covers the broader local picture.
Selling and Buying in South Jordan: FAQ
Can I make a South Jordan offer contingent on selling my current home?
Utah’s REPC lets you indicate that your purchase depends on selling a home you own, in Section 2.2. The details go in a separate addendum, which is what controls how it works.
If my South Jordan sale closes Friday, can I get the next keys Friday?
Not necessarily. The REPC separates settlement, funding and recording, and possession. Possession depends on what’s written in your purchase contract.
What happens if my buyer’s loan is delayed?
It depends on your contracts. Look at which purchase-side dates depend on your sale, and remember that extensions under the REPC have to be in writing.
Should I ask a lender about a HELOC or bridge loan before listing?
If you’re thinking about buying first, yes. A lender can tell you what’s available and whether you can carry both homes. The CFPB notes that borrowing against your home can put it at risk if you can’t repay.
Can I stay in my South Jordan home for a few days after it sells?
Possibly, if it’s written into your sale contract. Section 3.3 of the REPC lets the parties choose when possession transfers, and a longer stay as a renter requires a separate written agreement.
How much time should I allow between my sale and my next closing?
There’s no single right number. Build in room for funding and recording, the Closing Disclosure review window on a typical mortgage, and your possession terms. Your lender and title can help set realistic buffers.
Selling in South Jordan and Buying Your Next Home at the Same Time?
Send me your South Jordan address and target move window, and I’ll outline the decisions to check. Or call me, and we’ll talk through timing.